Student Loan Forgiveness 2026: Latest Federal Programs & Debt Relief
Student Loan Forgiveness 2026: Understanding the Latest Federal Programs and Potential Debt Relief for Millions
The landscape of student loan debt in the United States is constantly shifting, and for millions of borrowers, the prospect of student loan forgiveness in 2026 offers a beacon of hope. As policies evolve and new initiatives are introduced, staying informed about the latest federal programs and eligibility requirements is crucial. This comprehensive guide aims to demystify the current state of student loan forgiveness, providing detailed insights into what borrowers can expect in 2026 and beyond. We will delve into the various avenues for debt relief, examine recent updates, and help you understand the financial impact these programs can have on your life.
The Evolving Landscape of Student Loan Forgiveness
Student loan debt has become a significant burden for many Americans, impacting everything from homeownership to retirement planning. Recognizing this challenge, successive administrations and legislative bodies have sought to implement solutions. However, the path to comprehensive debt relief has been fraught with political debate, legal challenges, and administrative complexities. This fluid environment means that what was true yesterday regarding student loan forgiveness might not be today, making continuous updates essential.
The year 2026 is poised to be a critical period for many borrowers. While some programs are well-established, others are undergoing significant reforms, and new proposals may emerge. Our focus here is to provide a clear, actionable understanding of the programs most likely to impact borrowers seeking student loan forgiveness in 2026.
Why Staying Informed About Student Loan Forgiveness 2026 is Crucial
For individuals juggling student loan payments, the possibility of relief can be life-changing. But navigating the intricacies of federal programs requires diligence. Misinformation or a lack of understanding can lead to missed opportunities or incorrect financial planning. This article emphasizes the importance of understanding the fine print, eligibility criteria, and application processes for various student loan forgiveness programs.
Key Federal Student Loan Forgiveness Programs for 2026
Several federal programs offer pathways to student loan forgiveness. While their specifics can be complex, understanding the core principles of each is the first step toward determining your eligibility for student loan forgiveness in 2026.
1. Public Service Loan Forgiveness (PSLF)
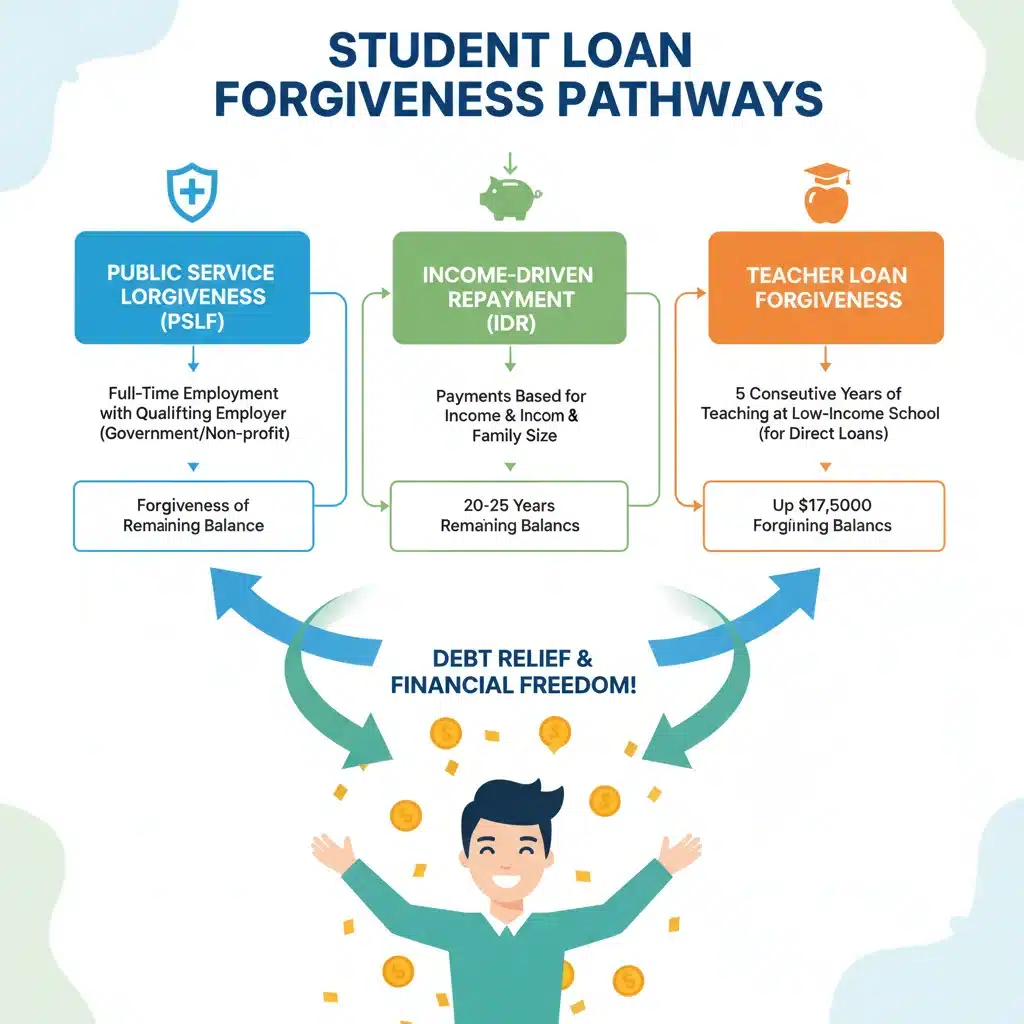
The Public Service Loan Forgiveness (PSLF) program remains one of the most significant avenues for debt relief for those working in qualifying public service jobs. Under PSLF, eligible federal student loan borrowers can have the remainder of their loan balance forgiven after making 120 qualifying monthly payments while working full-time for a qualifying employer.
Who Qualifies for PSLF?
- Eligible Loans: Only Direct Loans qualify. If you have FFEL Program loans or Perkins Loans, you might need to consolidate them into a Direct Consolidation Loan to become eligible.
- Qualifying Employment: This includes government organizations (federal, state, local, or tribal), not-for-profit organizations that are tax-exempt under Section 501(c)(3) of the Internal Revenue Code, and other not-for-profit organizations that provide certain public services.
- Full-Time Employment: Generally means working at least 30 hours per week.
- Qualifying Payments: Payments must be made under a qualifying income-driven repayment (IDR) plan.
Recent PSLF Updates and What to Expect in 2026
The PSLF program has undergone significant improvements in recent years, largely due to the PSLF Waiver and subsequent adjustments. While the waiver period has ended, many of its benefits have been integrated into the standard PSLF process and the broader IDR Account Adjustment. This means that past payments that previously didn’t count might now be credited towards the 120 payments. Borrowers should regularly check their payment count and ensure their employment is certified annually.
For student loan forgiveness 2026, the PSLF program is expected to continue its streamlined approach, making it easier for eligible borrowers to track their progress and receive forgiveness. However, it’s crucial to ensure all documentation is up-to-date and that you are enrolled in an eligible repayment plan.
2. Income-Driven Repayment (IDR) Plan Forgiveness
Income-Driven Repayment (IDR) plans are designed to make student loan payments more affordable by capping them at a percentage of your discretionary income. A key feature of IDR plans is that any remaining loan balance is forgiven after 20 or 25 years of payments, depending on the specific plan and whether you have loans for graduate study.
The SAVE Plan: A Game Changer for Student Loan Forgiveness 2026
The Saving on a Valuable Education (SAVE) Plan, which fully launched in 2024, is the newest IDR plan and offers the most generous terms for many borrowers. It replaced the REPAYE Plan and significantly reduces monthly payments for most borrowers, particularly those with lower incomes. The SAVE Plan also includes a provision for earlier forgiveness for borrowers with original loan balances of $12,000 or less, with forgiveness occurring after as few as 10 years of payments. This is a crucial development for those seeking student loan forgiveness in 2026.
Key Features of the SAVE Plan:
- Lower Payments: Payments on undergraduate loans are capped at 5% of discretionary income, down from 10% on other plans.
- Interest Subsidy: Unpaid interest does not accrue if you make your monthly payment, preventing your balance from growing.
- Earlier Forgiveness: Loans with original principal balances of $12,000 or less can be forgiven after 10 years of payments, with an additional year added for every $1,000 borrowed above that amount, up to 20 or 25 years.
The SAVE Plan is expected to be a primary driver of student loan forgiveness in 2026, offering substantial relief to millions. Borrowers not currently on the SAVE Plan should seriously consider enrolling to maximize their chances of debt relief.
IDR Account Adjustment (One-Time Adjustment)
The Department of Education has been implementing a one-time IDR Account Adjustment to ensure all eligible payments are counted towards IDR and PSLF forgiveness. This adjustment retroactively counts certain periods of deferment and forbearance that previously didn’t qualify. Many borrowers have already seen their payment counts updated, leading to immediate forgiveness for some. While the initial wave of adjustments is ongoing, its effects will continue to ripple into 2026, potentially pushing more borrowers closer to or over the forgiveness threshold.
3. Teacher Loan Forgiveness (TLF)
For educators, the Teacher Loan Forgiveness (TLF) program offers a direct path to relief. Highly qualified teachers who teach for five complete and consecutive academic years in low-income schools or educational service agencies can receive up to $17,500 in forgiveness on their Direct Subsidized and Unsubsidized Loans and their Subsidized and Unsubsidized Federal Stafford Loans.
Eligibility for TLF:
- Highly Qualified Teacher: Must meet state certification and licensing requirements.
- Low-Income School: Must be listed in the Teacher Cancellation Low Income (TCLI) Directory.
- Five Consecutive Years: Must complete five full and consecutive academic years of teaching.
While TLF is distinct from PSLF, some teachers may qualify for both. It’s important to understand the differences and determine which program offers the most benefit for your specific situation. This program will continue to be a vital resource for student loan forgiveness in 2026 for eligible teachers.
4. Other Loan Forgiveness and Discharge Options
Beyond PSLF, IDR, and TLF, several other specific circumstances can lead to student loan discharge or forgiveness:
- Total and Permanent Disability (TPD) Discharge: For borrowers who are totally and permanently disabled.
- Borrower Defense to Repayment: For borrowers whose schools engaged in misconduct or defrauded them.
- Closed School Discharge: For borrowers who could not complete their program because their school closed.
- Death Discharge: Federal student loans are discharged upon the death of the borrower.
While these are less common, they represent crucial safety nets for borrowers facing specific hardships. Borrowers should investigate these options if their circumstances align.
Understanding Eligibility and Application for Student Loan Forgiveness 2026
Eligibility for student loan forgiveness in 2026 is not always straightforward. Each program has specific criteria that must be met, and the application process can vary significantly. Attention to detail and consistent follow-up are key.
Consolidating Your Loans
For many borrowers, consolidating their federal student loans into a Direct Consolidation Loan is a critical step towards eligibility for certain forgiveness programs, particularly PSLF and some IDR plans. Consolidation can also simplify your payments by combining multiple loans into one with a single servicer.
It’s important to note that while consolidation can be beneficial, it also creates a new loan with a new interest rate (a weighted average of your previous loans). Consider the timing of consolidation carefully, especially if you have made significant progress toward forgiveness on existing loans, as it can reset your payment count in some cases (though the IDR Account Adjustment may mitigate this for many).
The Importance of Income-Driven Repayment Plans
As highlighted, IDR plans are foundational for both PSLF and IDR forgiveness. If you are not currently enrolled in an IDR plan, or if your income or family size has changed, it is vital to review your options. The SAVE Plan, in particular, offers substantial benefits that could dramatically reduce your monthly payments and accelerate your path to student loan forgiveness in 2026.
Annual Certification and Documentation
For programs like PSLF, annual certification of employment is mandatory. For IDR plans, you must recertify your income and family size annually. Failing to do so can lead to higher payments or even loss of progress towards forgiveness. Keep meticulous records of all payments, communications with your loan servicer, and employment certifications.
Financial Impact and Planning for Student Loan Forgiveness 2026
The potential for student loan forgiveness in 2026 has significant financial implications, not just for individual borrowers but for the broader economy. Understanding these impacts can help you plan more effectively.
Tax Implications of Forgiven Debt
Historically, forgiven debt has often been considered taxable income by the IRS. However, the American Rescue Plan Act of 2021 made most student loan forgiveness tax-free at the federal level through December 31, 2025. This means that if you receive student loan forgiveness in 2026 under a federal program, it will likely still be exempt from federal income tax. However, state tax laws vary, and some states may still consider forgiven debt as taxable income. It is crucial to consult with a tax professional to understand your specific state’s laws.
Budgeting and Financial Freedom
For those who achieve student loan forgiveness, the financial relief can be profound. It frees up income that can be directed towards other financial goals, such as saving for a down payment on a home, investing for retirement, paying off other debts, or simply improving daily cash flow. This newfound financial flexibility can significantly enhance economic well-being and stability.
Impact on Credit Scores
Successfully navigating student loan repayment and achieving forgiveness can positively impact your credit score. Reducing your debt-to-income ratio and eliminating a significant debt obligation can make you a more attractive borrower for other forms of credit. However, missing payments or defaulting on loans before forgiveness can severely damage your credit, so maintaining good payment habits is essential.
Future Outlook and Potential Changes Beyond 2026
While we focus on student loan forgiveness in 2026, it’s important to acknowledge that the policy landscape is always subject to change. Future presidential administrations, congressional actions, and legal challenges could all influence the availability and terms of forgiveness programs.
Potential for New Legislation
Advocates for broader student loan relief continue to push for more expansive forgiveness measures. While large-scale, universal forgiveness faces significant hurdles, targeted programs or adjustments to existing ones could still emerge. Staying informed through reputable sources like the Department of Education’s Federal Student Aid website is paramount.
The Role of Advocacy and Public Opinion
Public opinion and sustained advocacy play a crucial role in shaping student loan policy. As the economic impact of student debt remains a pressing issue, the conversation around relief and reform will continue. Borrowers and interested parties should remain engaged with these discussions.
Actionable Steps for Borrowers Seeking Student Loan Forgiveness in 2026
Given the complexities, taking proactive steps is vital for anyone hoping to achieve student loan forgiveness in 2026. Here’s a checklist of actions you should consider:
- Identify Your Loan Types: Determine if your loans are federal (Direct, FFEL, Perkins) or private. Federal loans are generally the only ones eligible for forgiveness.
- Review Your Repayment History: Access your loan history on studentaid.gov to check your payment counts for IDR and PSLF.
- Enroll in an IDR Plan: If you’re not already, consider enrolling in an Income-Driven Repayment plan, especially the SAVE Plan, if eligible.
- Certify Employment for PSLF: If you work in public service, submit your PSLF Employment Certification Form annually.
- Update Contact Information: Ensure your loan servicer and the Department of Education have your current contact information.
- Stay Informed: Regularly check official sources like studentaid.gov for the latest updates and announcements regarding student loan forgiveness.
- Consult a Financial Advisor: For personalized advice, consider speaking with a financial advisor or a student loan expert.
- Keep Detailed Records: Maintain copies of all loan documents, payment confirmations, and correspondence.
Common Misconceptions About Student Loan Forgiveness
With so much information circulating, it’s easy to fall prey to myths and misconceptions about student loan forgiveness. Let’s address a few common ones:
Myth 1: All Student Loans Will Be Forgiven Universally
While there have been proposals for broad, universal forgiveness, the current federal programs are targeted. Eligibility depends on specific loan types, employment, income, or other criteria. It’s unlikely that all student loans will be automatically forgiven for everyone in 2026.
Myth 2: You Don’t Need to Make Payments While Waiting for Forgiveness
This is a dangerous misconception. Unless your loans are in an approved deferment or forbearance, or you are in a payment pause period (like the one during the COVID-19 pandemic), you are generally required to make payments to qualify for forgiveness programs. Missing payments can lead to default and severely damage your credit.
Myth 3: Private Student Loans Are Eligible for Federal Forgiveness Programs
Federal student loan forgiveness programs, including PSLF and IDR forgiveness, apply only to federal student loans. Private student loans are issued by banks and other private lenders and have their own terms. While some private lenders may offer hardship programs, they are not covered by federal forgiveness initiatives.
Myth 4: Forgiveness is a Guaranteed Outcome if You Qualify
While qualifying makes you eligible, forgiveness is not always automatic. You must actively apply, submit necessary documentation, and ensure you meet all program requirements throughout the repayment period. Administrative errors or missed deadlines can delay or prevent forgiveness.
The Broader Economic Context of Student Loan Forgiveness
The discussion around student loan forgiveness in 2026 isn’t just about individual relief; it’s also about its potential impact on the national economy. Supporters argue that forgiveness can stimulate economic growth by freeing up consumer spending, reducing household debt burdens, and encouraging entrepreneurship. Critics, on the other hand, raise concerns about the cost to taxpayers, potential inflation, and the fairness to those who have already paid off their loans.
Regardless of where one stands on the economic debate, the sheer volume of student debt means that any significant policy changes will have ripple effects. As we move into 2026, policymakers will continue to weigh these factors, seeking a balance between providing relief and maintaining fiscal responsibility.
Conclusion: Navigating Your Path to Student Loan Forgiveness in 2026
The journey to student loan forgiveness in 2026 can be complex, but with the right information and proactive steps, it is an achievable goal for many. Whether you’re a public service worker, an educator, or simply struggling with high monthly payments, federal programs like PSLF, IDR plans (especially the SAVE Plan), and TLF offer substantial opportunities for debt relief.
Remember to regularly check your eligibility, stay informed about policy changes, and diligently manage your loan accounts. By taking these actions, you can significantly improve your chances of reducing your student loan burden and achieving greater financial freedom in 2026 and beyond. Don’t let the complexity deter you; empower yourself with knowledge and take control of your financial future.
For the most accurate and up-to-date information, always refer to the official Federal Student Aid website or consult with a trusted financial professional.