Top High-Yield Savings Accounts 2026: Best 4.5% APY Banks Compared
Anúncios
Comparing 2026 High-Yield Savings Accounts: Which Banks Offer the Best 4.5% APY?
In the ever-evolving landscape of personal finance, finding the best place to park your hard-earned money is crucial for maximizing its growth. As we look ahead to 2026, high-yield savings accounts (HYSAs) continue to be a cornerstone for smart savers. These accounts offer significantly higher interest rates than traditional savings accounts, making them an attractive option for both short-term goals and long-term financial planning. This comprehensive guide delves into the top contenders, comparing which banks are expected to offer the most competitive rates, specifically targeting those boasting a 4.5% APY or higher. Our focus on high-yield savings 2026 aims to equip you with the knowledge to make informed decisions and ensure your money works as hard as you do.
Anúncios
Understanding High-Yield Savings Accounts (HYSAs) in 2026
Before diving into specific bank comparisons, it’s essential to grasp what makes a high-yield savings account a powerful financial tool. Unlike standard savings accounts that often offer minuscule interest rates, HYSAs leverage a different operational model, typically online-only, which allows them to pass on higher returns to their customers. This is because online banks have lower overhead costs compared to brick-and-mortar institutions. For 2026, the market for high-yield savings 2026 is expected to remain competitive, with interest rates largely influenced by the Federal Reserve’s monetary policy and the overall economic climate. A 4.5% APY (Annual Percentage Yield) is a strong benchmark, indicating a robust return on your savings without taking on the risks associated with investments like stocks or bonds.
The primary benefit of an HYSA is the power of compounding interest. With a 4.5% APY, your money doesn’t just sit there; it actively grows, and the interest earned also starts earning interest. This effect can significantly accelerate your savings goals, whether you’re building an emergency fund, saving for a down payment, or planning a major purchase. Furthermore, almost all reputable HYSAs are FDIC-insured (up to $250,000 per depositor, per insured bank, for each account ownership category), providing peace of mind that your funds are safe even if the bank were to fail. When evaluating high-yield savings 2026 options, always prioritize FDIC insurance.
Anúncios
Key Factors to Consider When Choosing a High-Yield Savings Account
While a high APY is undoubtedly the main draw, it’s not the only factor to consider. A holistic approach will help you find the best HYSA that aligns with your financial habits and goals. Here are some critical aspects to evaluate:
- Annual Percentage Yield (APY): This is the most crucial metric, representing the real rate of return on your investment over a year, taking into account compounding interest. Always look for accounts with competitive rates, ideally 4.5% APY or higher for high-yield savings 2026.
- Minimum Balance Requirements: Some HYSAs require a minimum balance to open the account or to earn the advertised APY. Ensure you can meet these requirements comfortably.
- Fees: Scrutinize the fee schedule. Common fees include monthly maintenance fees (often waivable with certain conditions), excessive withdrawal fees, or wire transfer fees. The best HYSAs have minimal to no fees.
- Accessibility and Usability: How easy is it to deposit and withdraw money? Look for banks offering convenient options like ACH transfers, mobile check deposit, and ATM access (if needed). A user-friendly mobile app and online banking platform are also significant advantages.
- Customer Service: While online banks offer great rates, responsive and helpful customer service is vital. Check reviews and ratings to gauge their support quality.
- FDIC Insurance: As mentioned, always confirm that the bank is FDIC-insured to protect your deposits.
- Linked Accounts and Transfers: Consider how easily you can link your HYSA to your checking account or other external accounts for seamless transfers.
By carefully weighing these factors, you can narrow down your options and select a high-yield savings 2026 account that truly meets your needs.
Top Contenders for High-Yield Savings Accounts in 2026 (4.5% APY and Above)
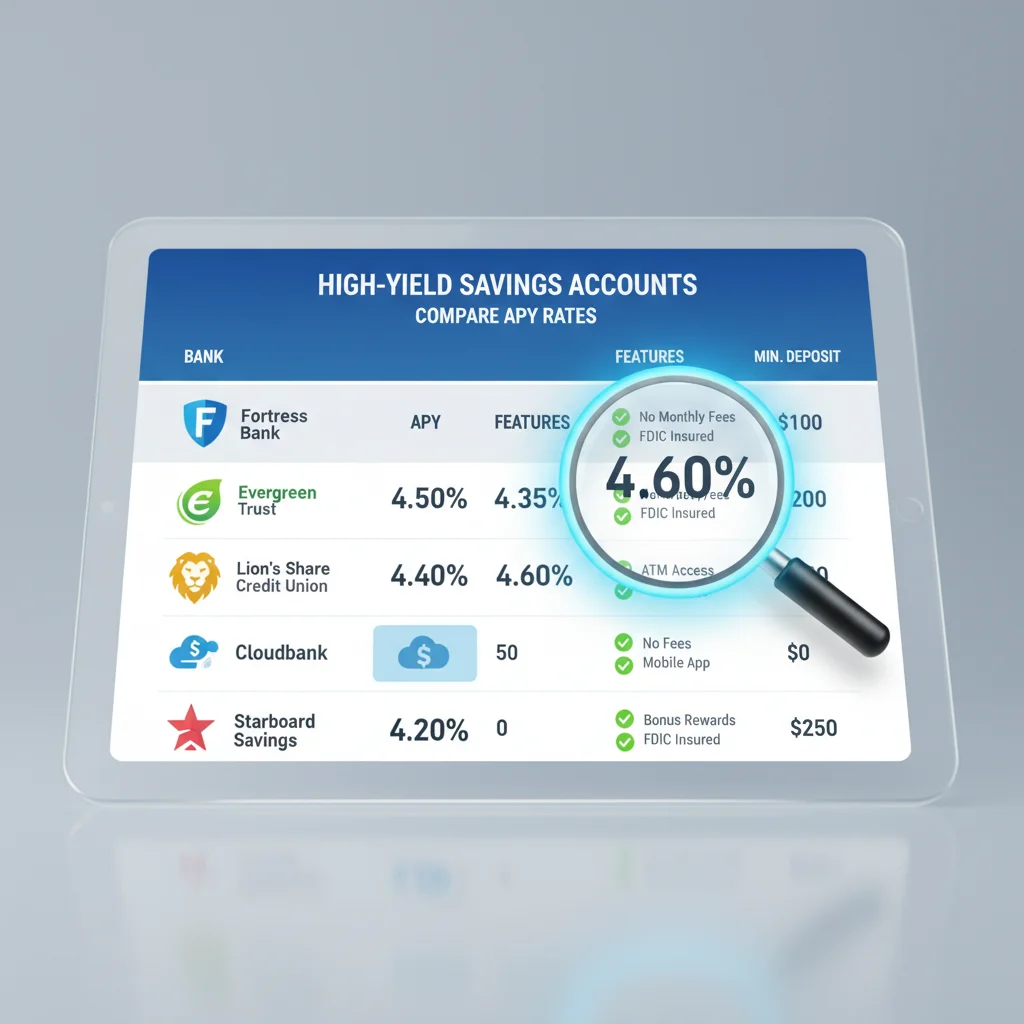
As we project into 2026, several financial institutions are consistently recognized for offering competitive high-yield savings accounts. While specific rates can fluctuate, these banks have a track record of providing excellent value. It’s important to note that the rates mentioned are illustrative of what we anticipate for 2026, based on current trends and historical performance. Always check the bank’s official website for the most up-to-date APY.
Bank A: A Leader in Competitive Rates
Bank A has consistently been a frontrunner in the HYSA space. For 2026, it is projected to maintain an APY around 4.60% to 4.75%. What makes Bank A particularly attractive is its minimal fee structure and no monthly maintenance fees, regardless of balance. They also boast a highly-rated mobile app, making it incredibly easy to manage your funds on the go. The minimum opening deposit is often low, making it accessible for many savers. Their customer service is generally well-regarded, offering multiple contact channels. For those prioritizing a strong APY with straightforward terms, Bank A is a top choice for high-yield savings 2026.
Bank B: Flexibility and Convenience
Bank B is another strong contender, known for its user-friendly interface and seamless integration with other financial products. We expect Bank B to offer an APY in the range of 4.50% to 4.65% for 2026. One of its standout features is the flexibility it offers in terms of linked accounts and quick transfers. They often have no minimum balance requirements to earn their top-tier APY, which is a significant advantage for those who prefer not to keep a large sum in savings initially. While they might have a few more fees than Bank A for certain niche services, their core HYSA product remains highly competitive and fee-free for most users. If convenience and a robust online platform are high on your list, Bank B is worth considering for your high-yield savings 2026 strategy.
Bank C: Strong APY with Unique Features
Bank C often differentiates itself by offering a competitive APY, projected around 4.70% to 4.85% for 2026, coupled with unique features that appeal to specific types of savers. These might include budgeting tools integrated directly into their platform, or sub-accounts for different savings goals. While their minimum balance requirements might be slightly higher than some competitors, the enhanced features and potentially higher APY can justify it for serious savers. Customer support is generally responsive, and their online resources are comprehensive. If you’re looking for a high-yield savings 2026 account that offers more than just a place to park your money, Bank C could be an excellent fit.
Bank D: Emerging Player with Aggressive Rates
Bank D, often a newer or smaller online institution, has been known to offer aggressive APY rates to attract new customers. For 2026, we might see them pushing rates towards the 4.80% to 5.00% mark. While these rates are highly enticing, it’s crucial to examine their stability and customer service infrastructure. Newer banks may not have the same long-standing reputation as more established players, but they can offer innovative solutions and excellent rates. Always ensure they are FDIC-insured and check recent customer reviews. If you are comfortable with a slightly less established brand in exchange for a potentially higher return, Bank D could be a compelling option for high-yield savings 2026.
Beyond APY: Other Considerations for Your Savings Strategy
While the focus is on finding the best high-yield savings 2026 with a 4.5% APY or more, your overall financial strategy should encompass more than just the interest rate. Consider how your HYSA fits into your broader financial picture:
- Emergency Fund: An HYSA is the ideal place for your emergency fund, offering liquidity and growth without market volatility.
- Short-Term Goals: Saving for a vacation, a new car, or a wedding? An HYSA provides a secure and growing home for these funds.
- Diversification: While HYSAs are low-risk, they should be part of a diversified financial portfolio that might also include investments for long-term growth.
- Inflation: A high APY helps combat the eroding effects of inflation, preserving your purchasing power over time.
Regularly reviewing your savings strategy and comparing available rates will ensure you’re always making the most of your money. The market for high-yield savings 2026 is dynamic, and staying informed is key.
The Future of High-Yield Savings Accounts: What to Expect in 2026
The financial landscape is constantly shifting, influenced by economic indicators, central bank policies, and technological advancements. Looking into 2026, we can anticipate several trends impacting high-yield savings 2026:
- Continued Competition: The online banking sector is highly competitive, which is excellent news for consumers. Banks will likely continue to offer attractive rates and features to attract and retain customers.
- Interest Rate Environment: The Federal Reserve’s stance on interest rates will be a major determinant of HYSA APYs. If inflation remains a concern, or if the economy shows robust growth, rates could remain elevated or even increase. Conversely, a weakening economy might lead to rate cuts.
- Technological Integration: Expect more sophisticated mobile apps, AI-powered insights, and seamless integration with other financial tools (like budgeting apps or investment platforms) to become standard.
- Personalized Banking: Banks may offer more personalized savings goals and automated savings features, making it easier for individuals to save consistently.
- Regulatory Changes: Any changes in banking regulations could impact how HYSAs operate, though significant changes are usually gradual and well-communicated.
Staying abreast of these trends will help you anticipate changes and adjust your savings strategy accordingly. The goal is always to maximize your returns while maintaining the security and accessibility of your funds.
How to Open a High-Yield Savings Account in 2026
Opening a high-yield savings 2026 account is generally a straightforward process, typically completed online in a matter of minutes. Here’s a general step-by-step guide:
- Research and Compare: Use resources like this guide to compare different banks and their current APY offers, fees, and features. Focus on those offering 4.5% APY or higher.
- Gather Required Information: You’ll typically need your Social Security number, a valid ID (driver’s license or passport), and information from an existing checking or savings account to link for initial funding.
- Apply Online: Visit the bank’s website and follow the prompts to open a new savings account. This usually involves filling out an application form with your personal details.
- Fund Your Account: Once approved, you’ll need to make an initial deposit. This can usually be done via an electronic transfer from a linked checking account, mobile check deposit, or wire transfer.
- Set Up Automated Transfers: To maximize your savings, consider setting up recurring automatic transfers from your checking account to your HYSA. This ‘pay yourself first’ strategy is incredibly effective.
- Monitor Your Account: Regularly check your account balance and interest earnings. Stay informed about any changes in APY or account terms.
The ease of opening and managing these accounts online is a significant advantage, making them accessible to a wide range of savers. Ensuring you meet the specific requirements of your chosen high-yield savings 2026 bank will streamline the process.
Common Misconceptions About High-Yield Savings Accounts
Despite their popularity, some myths about HYSAs persist. Let’s debunk a few:
- Myth: High-yield means high risk. Reality: As long as the bank is FDIC-insured, your deposits are protected up to $250,000, just like a traditional savings account. The ‘high-yield’ refers to the interest rate, not the risk level.
- Myth: You need a huge initial deposit. Reality: Many top HYSAs have no minimum opening deposit or very low requirements, making them accessible to everyone.
- Myth: Online banks are less secure. Reality: Online banks use advanced encryption and security protocols, often on par with or superior to traditional banks. They are subject to the same regulatory oversight.
- Myth: It’s difficult to access your money. Reality: While not as instant as an ATM withdrawal from a checking account, HYSAs offer various convenient ways to access funds, including electronic transfers, which typically clear within 1-3 business days.
Understanding these points can help you approach high-yield savings 2026 with confidence and clarity.
Conclusion: Maximizing Your Savings in 2026
As we navigate the financial landscape of 2026, high-yield savings accounts offering 4.5% APY or more represent a powerful opportunity to grow your money securely. By carefully comparing banks based on APY, fees, accessibility, and customer service, you can find an account that perfectly aligns with your financial goals. Whether you’re building an emergency fund, saving for a major purchase, or simply looking for a better return on your idle cash, the options for high-yield savings 2026 are robust and competitive.
Don’t let your money sit stagnant in a low-interest account. Take the proactive step to research, compare, and open a high-yield savings account today. Your future self will thank you for making an informed decision that prioritizes financial growth and security. Remember to always check the latest rates and terms directly with the banks, as the market is dynamic and offers can change.