Smart Money Moves Q3 2026: Rebalancing Your Portfolio for Maximum Returns
Smart Money Moves for Q3 2026: Rebalancing Your Portfolio for Maximum Returns (TIME-SENSITIVE)
As we step into Q3 2026, the financial landscape continues to evolve, presenting both opportunities and challenges for investors. The astute investor understands that a ‘set it and forget it’ approach rarely yields optimal results in a dynamic market. Instead, proactive engagement, particularly through consistent portfolio rebalancing strategy, is paramount. This comprehensive guide will delve into the critical aspects of rebalancing your investment portfolio during this pivotal quarter, aiming to not only protect your gains but also to position you for maximum returns.
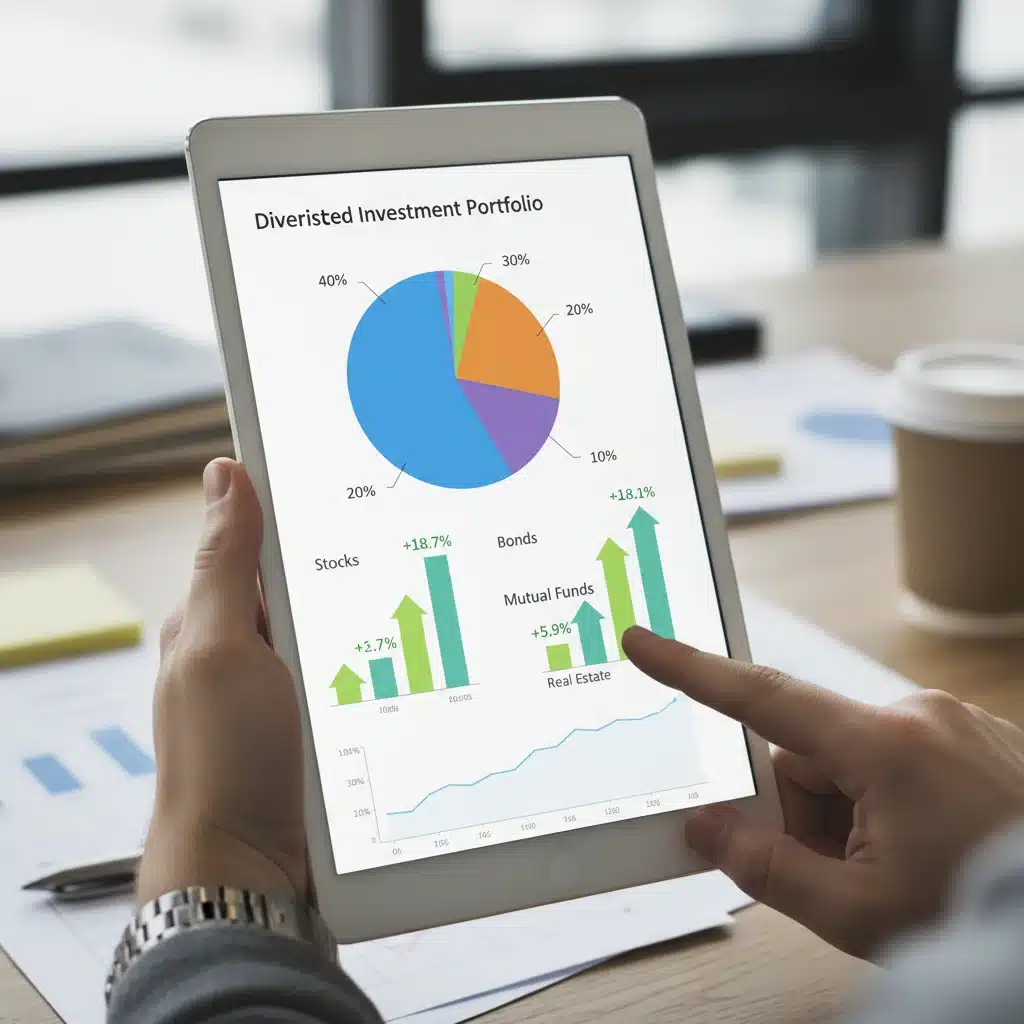
The concept of portfolio rebalancing strategy is simple yet profound: it involves adjusting the weightings of your asset classes to bring them back to their original or desired allocation. Over time, market movements can cause your portfolio’s asset allocation to drift. For instance, if stocks have performed exceptionally well, they might now represent a larger percentage of your portfolio than you initially intended, increasing your overall risk exposure. Conversely, underperforming assets might shrink, reducing their potential contribution to future growth. Q3 2026 offers a timely juncture to assess these shifts and make informed adjustments.
Why Q3 2026 Demands a Strategic Portfolio Rebalancing Strategy
Every quarter brings its unique set of economic indicators, geopolitical events, and technological advancements that can influence market performance. Q3 2026 is no exception. We are currently observing a confluence of factors that make a thorough review of your portfolio rebalancing strategy not just advisable, but essential. These factors include:
- Evolving Inflationary Pressures: While some inflationary pressures may have moderated, others could be resurfacing due to supply chain adjustments or shifts in consumer demand. How these pressures manifest will significantly impact the performance of different asset classes.
- Interest Rate Environment: Central bank policies regarding interest rates continue to be a dominant force. Changes in rates affect everything from bond yields to corporate borrowing costs and equity valuations. Understanding the trajectory of interest rates is crucial for your portfolio rebalancing strategy.
- Technological Disruption and Innovation: The pace of technological change shows no signs of slowing. Emerging technologies, from AI advancements to new energy solutions, are creating both new investment opportunities and potential risks for established industries. Your portfolio should reflect these shifts.
- Geopolitical Developments: Global political stability and international trade relations can have far-reaching effects on markets. Monitoring these developments and understanding their potential impact on your holdings is a key component of a robust portfolio rebalancing strategy.
- Sectoral Performance Divergence: Different sectors of the economy rarely move in lockstep. Some might be experiencing boom cycles while others face headwinds. A Q3 2026 review allows you to identify these divergences and adjust your exposure accordingly.
Ignoring these dynamics can lead to a portfolio that no longer aligns with your risk tolerance or financial goals. A thoughtful portfolio rebalancing strategy ensures you remain diversified, manage risk effectively, and capture growth opportunities.
Understanding Your Current Portfolio Allocation: The First Step
Before you can rebalance, you must first understand where your portfolio stands. This involves a detailed analysis of your current asset allocation. Pull up your latest investment statements and categorize your holdings by asset class: stocks (broken down by market capitalization, geography, and sector), bonds (by type, duration, and credit quality), real estate, commodities, and alternative investments. Compare these current percentages to your target allocation. Your target allocation should be a reflection of your:
- Risk Tolerance: How much volatility are you comfortable with? A higher risk tolerance might justify a larger allocation to equities, while a lower tolerance would lean towards more conservative assets like bonds.
- Time Horizon: When do you need the money? A longer time horizon allows for greater risk-taking, as there is more time to recover from market downturns. Shorter time horizons typically call for a more conservative approach.
- Financial Goals: What are you saving for? Retirement, a down payment on a house, or your children’s education? Each goal might have different timelines and require specific growth rates.
Many investors initially set their target allocation based on these factors but then fail to revisit them. Q3 2026 is an ideal time to not only check your current allocation but also to reassess if your original target allocation still holds true given any changes in your personal circumstances or market outlook. This foundational step is indispensable for an effective portfolio rebalancing strategy.
Methods of Portfolio Rebalancing Strategy: Which One is Right for You?
There are several approaches to implementing a portfolio rebalancing strategy, each with its own merits. The best method for you will depend on your investment style, time availability, and tax considerations.
1. Calendar-Based Rebalancing
This is perhaps the most straightforward method. You simply rebalance your portfolio at predetermined intervals, such as quarterly, semi-annually, or annually. Q3 2026 offers a natural calendar-based trigger for this process. The advantage of this method is its simplicity and discipline; it removes emotion from the decision-making process. The downside is that it might force you to rebalance during unfavorable market conditions or miss opportunities to adjust when significant shifts occur between rebalancing dates.
2. Threshold-Based Rebalancing
With this method, you only rebalance when an asset class deviates by a certain percentage from its target allocation. For example, if your target allocation for stocks is 60% and you set a threshold of 5%, you would rebalance only when stocks reach 65% or fall to 55%. This method is more responsive to market movements than calendar-based rebalancing and can potentially reduce transaction costs by avoiding unnecessary trades. However, it requires more active monitoring of your portfolio.
3. Hybrid Rebalancing
As the name suggests, this method combines elements of both calendar-based and threshold-based rebalancing. You might set a primary rebalancing schedule (e.g., annually) but also allow for rebalancing if a certain threshold is breached before the scheduled date. This offers a good balance between discipline and responsiveness, making it a popular choice for many investors seeking an effective portfolio rebalancing strategy.
4. Rebalancing by Cash Flows
Instead of selling appreciated assets, you can use new cash flows (e.g., contributions from your salary, dividends, or bond interest) to buy underperforming assets. This is a tax-efficient way to rebalance, as it avoids capital gains taxes that might be incurred from selling appreciated holdings. This method is particularly effective for investors who regularly contribute to their portfolios. For Q3 2026, consider directing new investments towards areas that have fallen below their target allocation.
Key Considerations for Your Q3 2026 Portfolio Rebalancing Strategy
Beyond choosing a rebalancing method, several factors should guide your decisions during Q3 2026:
Tax Implications
Selling appreciated assets can trigger capital gains taxes. Be mindful of whether your investments are held in tax-advantaged accounts (like 401(k)s or IRAs), where rebalancing typically doesn’t incur immediate tax consequences, or taxable accounts. In taxable accounts, consider strategies like tax-loss harvesting (selling losing investments to offset gains) or rebalancing with new contributions to minimize your tax bill. Always consult with a tax professional to understand the specific implications for your situation.
Transaction Costs
Frequent trading, even for rebalancing, can lead to significant transaction costs (commissions, bid-ask spreads). Factor these costs into your portfolio rebalancing strategy. Using low-cost index funds or ETFs can help mitigate these expenses, as can choosing a rebalancing method that minimizes unnecessary trades.
Market Outlook for Q3 2026
While rebalancing is primarily about maintaining your desired risk profile, it’s also wise to have a general understanding of the market outlook. Are there specific sectors or regions poised for growth or potential downturns? For instance, if analysts predict continued strength in technology stocks for Q3 2026, you might allow that portion of your portfolio to slightly exceed its target before rebalancing, or conversely, trim it if you anticipate a correction. However, be cautious not to let market timing overshadow your long-term strategy.
Diversification Beyond Asset Classes
True diversification extends beyond just different asset classes. Within your equity holdings, ensure you are diversified across:
- Market Capitalization: Large-cap, mid-cap, and small-cap stocks.
- Geographic Regions: Domestic, international developed, and emerging markets.
- Sectors: Technology, healthcare, consumer staples, financials, industrials, etc.
Similarly, for fixed income, consider diversification across bond types (government, corporate, municipal) and maturities. A robust portfolio rebalancing strategy in Q3 2026 will address these layers of diversification.
Practical Steps for Your Q3 2026 Portfolio Rebalancing Strategy
Let’s outline a step-by-step approach to effectively rebalance your portfolio this quarter:
Step 1: Review Your Financial Goals and Risk Tolerance
Before touching any investments, take a moment to reaffirm your financial goals. Have they changed? Is your retirement timeline still the same? Has your comfort level with risk shifted due to personal circumstances or market experiences? Your answers will confirm or adjust your target asset allocation, which is the cornerstone of your portfolio rebalancing strategy.
Step 2: Analyze Your Current Asset Allocation
Gather all your investment statements. Create a clear picture of your current holdings across all accounts. Calculate the percentage each asset class represents in your total portfolio. Many brokerage platforms offer tools to help with this. Compare these actual percentages against your updated target allocation.
Step 3: Identify Deviations and Decide on Your Rebalancing Method
Pinpoint which asset classes have drifted significantly from their targets. Based on your chosen rebalancing method (calendar, threshold, hybrid, or cash flow), determine which assets need to be bought or sold. For instance, if your target is 60% stocks and they’ve grown to 70%, you’ll need to trim stocks. If bonds have shrunk from a target of 30% to 20%, you’ll need to add to your bond holdings.
Step 4: Execute the Trades (Thoughtfully)
When executing trades, prioritize tax efficiency. In taxable accounts, consider selling assets with losses first to offset gains. If you have new money to invest, direct it towards underperforming asset classes to bring them back to target. If selling is necessary, try to sell in smaller increments to avoid major market impact, especially with less liquid assets. For Q3 2026, consider the immediate market sentiment, but always keep your long-term strategy in sight.
Step 5: Document and Monitor
Keep a record of your rebalancing decisions. This will help you track your progress and learn from your strategy over time. After rebalancing, continue to monitor your portfolio regularly, even if you’re using a calendar-based approach. Market events can sometimes warrant an interim review, especially during a volatile Q3 2026.
Common Pitfalls to Avoid in Your Portfolio Rebalancing Strategy
Even with the best intentions, investors can make mistakes during rebalancing. Be aware of these common pitfalls:
- Emotional Decisions: Don’t let fear or greed dictate your rebalancing. Selling assets that have fallen significantly out of fear or holding onto overvalued assets out of greed can undermine your long-term goals. Stick to your predetermined plan.
- Ignoring Tax Consequences: As mentioned, taxes can significantly erode your returns. Always factor them into your rebalancing decisions, especially in taxable accounts.
- Over-Rebalancing: Too frequent rebalancing, especially with small deviations, can lead to excessive transaction costs and potential tax liabilities. Unless you’re using a strict threshold, avoid constant tweaking.
- Neglecting Your Goals: The primary purpose of rebalancing is to maintain alignment with your financial goals and risk tolerance. If you lose sight of these, your portfolio rebalancing strategy becomes rudderless.
- Failing to Diversify Adequately: While rebalancing brings your asset classes back to target, ensure that within those asset classes, you are still broadly diversified across sectors, geographies, and market caps.
Expert Insights for Q3 2026: Refining Your Portfolio Rebalancing Strategy
While the core principles of rebalancing remain constant, adapting them to the current environment is key. Here are some expert insights relevant to Q3 2026:
- The Role of Alternative Investments: Consider whether alternative investments (e.g., private equity, hedge funds, real estate, commodities) should play a role in your diversified portfolio. While often less liquid, they can provide diversification benefits and uncorrelated returns, especially in volatile periods. If you have exposure, ensure it aligns with your overall portfolio rebalancing strategy.
- Sustainable Investing (ESG): Environmental, Social, and Governance (ESG) factors are increasingly influencing corporate performance and investor sentiment. Reviewing your portfolio through an ESG lens during Q3 2026 can align your investments with your values and potentially identify companies with stronger long-term resilience.
- Cash as an Asset Class: In uncertain times, cash can be a valuable asset. While it doesn’t offer significant returns, it provides liquidity and optionality to seize opportunities when markets dip. Rebalancing might involve increasing your cash position slightly if you anticipate significant market volatility.
- Dollar-Cost Averaging Benefits: If you’re regularly contributing to your investments, continue to leverage dollar-cost averaging. This strategy naturally aids in rebalancing by allowing you to buy more shares when prices are low and fewer when prices are high, smoothing out your average purchase price.
- Consult a Financial Advisor: For complex portfolios or if you’re unsure about the best approach, a qualified financial advisor can provide personalized guidance. They can help you assess your risk tolerance, set realistic goals, and implement a sophisticated portfolio rebalancing strategy tailored to your specific needs for Q3 2026 and beyond.
The Long-Term Benefits of a Consistent Portfolio Rebalancing Strategy
The immediate impact of rebalancing might seem minor, but its long-term benefits are substantial. A consistent portfolio rebalancing strategy helps you:
- Maintain Your Desired Risk Level: Prevents your portfolio from becoming overly concentrated in risky assets during bull markets or too conservative during bear markets.
- Buy Low, Sell High (Automatically): By trimming appreciated assets and adding to underperforming ones, you are inherently engaging in a disciplined form of ‘buying low and selling high,’ even if it’s not a conscious market-timing decision.
- Enhance Diversification: Ensures your portfolio remains diversified across different asset classes, reducing overall risk and increasing the potential for stable returns.
- Stay Aligned with Financial Goals: Keeps your investment strategy on track with your evolving life circumstances and financial objectives.
- Improve Long-Term Returns: Studies have shown that rebalancing can lead to superior risk-adjusted returns over the long run compared to a portfolio that is never adjusted.
As we navigate through Q3 2026, the importance of these benefits cannot be overstated. The global economy is a complex system, and while predicting its exact movements is impossible, preparing for various scenarios through a robust portfolio rebalancing strategy is entirely within your control.
Conclusion: Make Your Q3 2026 Portfolio Rebalancing Strategy a Priority
Q3 2026 is a critical period for investors to review and adjust their portfolios. Market dynamics are constantly shifting, and a passive approach can leave your investments vulnerable or cause you to miss out on significant opportunities. By understanding your current allocation, reassessing your goals and risk tolerance, choosing an appropriate rebalancing method, and being mindful of tax implications, you can implement an effective portfolio rebalancing strategy.
This process is not merely about maintaining percentages; it’s about disciplined risk management, strategic positioning, and ultimately, maximizing your chances of achieving your long-term financial aspirations. Don’t let this quarter pass without giving your portfolio the attention it deserves. A smart, timely rebalance in Q3 2026 could be one of the most impactful money moves you make all year.